Chime® – Fee-Free Banking

- 245.55K Reviews
- 4.7
- Downloads
- 10,000,000+
 Analysis by Appgk
I judge a banking app less by how many buttons it offers than by whether it helps me make a sensible decision when money is tight, payday is near, or a small purchase threatens to derail a plan. Chime – Mobile Banking is built around that everyday view of money: access through a phone, fewer routine fees, and tools meant to make pay and saving easier to manage. It is a finance app from Chime, and its appeal is clearest for people who want a straightforward account experience rather than a branch-first relationship.
What to consider before choosing a banking app
Before switching, I’d ask what problem I actually want the app to solve. Is it a recurring monthly charge, difficulty keeping savings separate, or the gap between finishing work and receiving pay? Chime’s strongest pitch is aimed at those practical pain points. If you mainly want a place to organize everyday banking and value features tied to direct deposit and saving habits, it is worth a closer look.
The basic trade-off is that convenience is not the same as a complete fit for every financial life. A mobile-first account can suit someone who handles routine tasks from a phone, while someone who depends on in-person help or a particular service from an existing bank may prefer to keep that relationship. I would compare the tasks I do most often—not just the headline benefits—before moving my primary money.
Where Chime can make everyday money easier
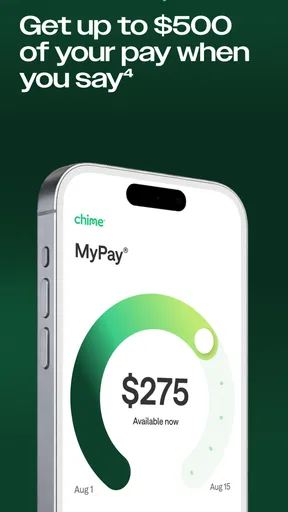
Chime’s early-pay feature can be useful when a paycheck arrives before a bill is due, but I would treat it as a timing convenience, not as extra income. In a realistic week, I might use an incoming direct deposit to cover a scheduled expense and leave the remainder for groceries and savings. The practical benefit is having more visibility over that sequence; it does not remove the need to check the due dates and keep enough money available.
There is also a useful behavioral angle to the savings tools. Automatic round-ups can turn frequent card purchases into small transfers without asking me to remember a separate savings session. That works best when I treat the transferred change as money I have already set aside, rather than a balance I can casually spend again. If my budget is very tight, I’d first check whether automatic saving feels comfortable alongside upcoming bills.
The app is free to download, and it has a 4.7 average from around 946,000 ratings. It has more than 10 million installs, a broad sign that many people have tried it, though popularity alone does not tell me whether its account setup suits my needs. Its Everyone age rating, version 5.301.0, and minimum operating-system requirement of 10 are useful compatibility details to check before installing.
Seamless Banking Experience
First off, Chime – Mobile Banking makes managing your money feel ridiculously easy. You’ve got your checking and savings accounts all in one place, and switching between them is as smooth as butter. The app’s interface is clean and intuitive, which is a big plus if you’re not a fan of clunky apps.
News Picks to Read Next
View All News


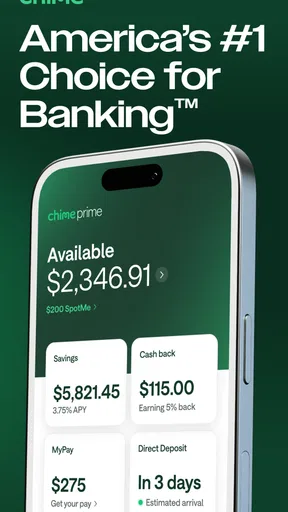
One of the coolest features is getting your paycheck up to two days early with direct deposit. I mean, who doesn’t want their money sooner, right? It’s like a little treat to yourself every payday. Plus, there are no hidden fees lurking around the corner. Say goodbye to those annoying maintenance fees and hello to fee-free overdraft up to $200, which is a lifesaver when you’re in a pinch.
Saving Made Easy
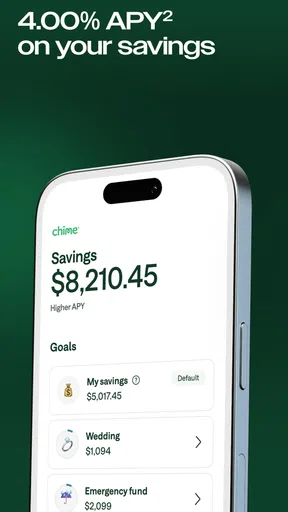
Now, let’s talk about saving money. Chime offers an automatic savings feature that rounds up your purchases to the nearest dollar and dumps the change into your savings account. It’s like having a tiny piggy bank that grows over time without you even noticing. Pretty neat, huh?
Best Parts of Chime® – Fee-Free Banking
Things to Keep in Mind About Chime® – Fee-Free Banking
If you’re the kind of person who struggles with saving, this feature makes it almost effortless. And with the high-yield savings account, your money doesn’t just sit there—it actually works for you. It’s a smart way to grow your savings without breaking a sweat.
Putting the tools to work without losing track
A small but useful approach is to give checking and savings different jobs. I’d keep ordinary spending money in checking and think of the savings balance as reserved for a named goal, such as a car repair or a future bill. That mental boundary matters more than the round-up itself: if every transfer is immediately treated as spendable, the feature may create activity without building a lasting cushion.
Early access to pay can also change the rhythm of a budget. I would avoid shifting every bill date or spending plan around an assumed early arrival; the useful habit is to budget around the normal payday and regard earlier availability as breathing room when it happens. That keeps a timing benefit from becoming a dependency. Likewise, an overdraft option can help with a short-lived cash-flow gap, but it is not a replacement for checking balances or planning for recurring expenses.
For someone paid by direct deposit, the first practical question is whether their pay arrangement fits the way the app’s early-pay feature works. I’d confirm the deposit is set up correctly and watch the account activity around the first incoming payment before building bill timing around it. For someone who receives income in other ways, the early-pay benefit may matter less, so the app should be judged by the everyday account and saving experience instead.
Security and Support
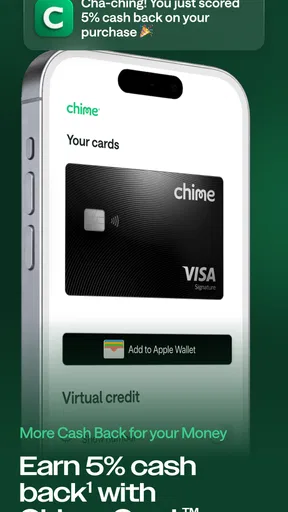
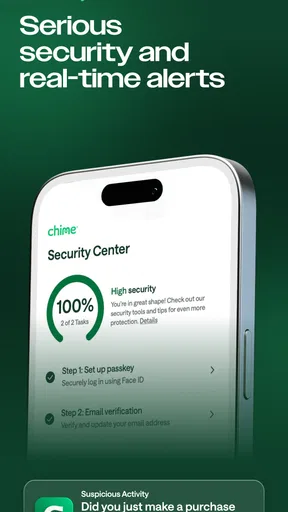
Security is a big deal with any banking app, and Chime doesn’t disappoint. They’ve got security features like two-factor authentication and real-time transaction alerts that keep you in the loop. If anything looks fishy, you can easily turn off your card directly from the app. It’s all about keeping your money safe and sound.
And if you ever find yourself in a pickle, Chime’s customer support is available 24/7. Whether you prefer chatting in-app or giving them a call, they’ve got your back. It’s reassuring to know help is just a tap away.
Screenshots
When another option may be a better match
Compared with a traditional bank app, Chime’s emphasis is on managing money digitally rather than making a branch part of the routine. If I regularly need to speak with someone face to face, deposit or handle cash through a specific local setup, or rely on a banking service that I already use elsewhere, I would compare those needs carefully before making it my main account. A familiar bank may be more convenient when its existing arrangements are hard to replace.
It is also worth comparing it with budgeting apps and other digital banking options without assuming they do the same job. A budgeting tool may be better if my main need is to see spending across several accounts; an account-focused app is more appealing when I want day-to-day banking and saving tools together. I would not switch just because one interface looks simpler. I’d list the features I use weekly, then make sure the new setup covers those tasks in a way I understand.
People who value predictable, low-friction banking may find Chime a good fit, especially if direct deposit and automatic saving are relevant to their routine. It may be less compelling for someone who wants extensive in-person services, already has a bank setup that works well, or prefers to keep spending analysis separate from the account itself. There is no benefit in moving everything if the new workflow creates more work than it removes.
Security habits and practical limits
Alerts and the ability to turn off a card are helpful because they make a response easier when something seems wrong, but they work best when notifications are enabled and checked. I’d take a moment after setup to make sure transaction alerts are useful rather than so frequent that I start ignoring them. If I notice an unfamiliar transaction, I’d use the available controls promptly and contact support instead of assuming a card lock alone resolves every account concern.
Before relying on any banking app as the only place to access money, I would also think through the transition. Update incoming deposits and recurring payments deliberately, keep track of which account is responsible for each bill, and leave enough time to catch a payment that is still tied to the old account. That is ordinary switching work, but it is where a convenient app can become a headache if rushed.
For a first-time user, I’d explore the account layout before moving every financial task into it. Check how checking and savings appear together, understand how the automatic saving behavior fits your spending, and make sure the phone’s operating system meets the app’s requirement. These small checks answer the practical question of whether it feels manageable before it becomes central to payday and bills.
How I’d decide whether to switch
My preference would be to treat the move as a workflow change, not a quick download. I’d start by identifying the deposits and bills that matter most, then change them in a deliberate order and monitor the first cycle. I’d keep my old account available until I was comfortable that regular payments were reaching the intended place. This is especially sensible for anyone whose rent, utilities, or other essential expenses depend on exact timing.
Chime is free, but the cost of switching is measured in attention and coordination rather than the download. You may need to update payment details, learn a new account routine, and decide how much to keep in checking versus savings. If the fee-free structure and mobile tools solve a genuine recurring frustration, that effort may feel worthwhile. If your current account already does what you need, there is no reason to change solely for novelty.
The Verdict
All in all, Chime is a solid choice if you’re looking to simplify your banking experience. It’s packed with features that make managing money less of a hassle and more of a breeze. From early paydays to fee-free banking, it’s like having a bank that actually works for you, not the other way around.
If you’re tired of traditional banks and their endless fees, give Chime – Mobile Banking a shot. It might just be the fresh start your finances need.
My recommendation is to consider it when you want a mobile-first way to handle everyday banking, value the direct-deposit and savings approach, and are comfortable managing the transition yourself. I would pause if branch access or a specific existing banking service is essential, or if early access to pay is the only reason it appeals. Used with a realistic budget and a little care around bill changes, Chime can make routine money management feel more orderly; the best reason to choose it is that its particular tools fit your habits, not simply that they sound convenient.
Chime® – Fee-Free Banking FAQ
What features does Chime offer for mobile banking?
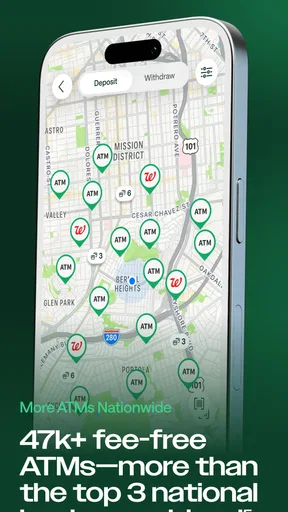
Chime provides a range of features designed to simplify your banking experience. These include early direct deposits, no hidden fees, a savings account with automatic savings options, and a user-friendly interface. Additionally, the app offers real-time transaction alerts, bill payment options, and a network of over 60,000 fee-free ATMs.
Is Chime a secure platform for managing my finances?
Yes, Chime employs robust security measures to protect your financial information. The app uses encryption and multi-factor authentication to secure your account. Moreover, Chime is FDIC insured through its banking partners, ensuring that your deposits are safe up to the legal limit.
How does Chime’s early direct deposit feature work?
Chime allows you to receive your paycheck up to two days earlier than traditional banks by posting your direct deposit as soon as it is received. This feature depends on your employer or benefits provider's payment schedule, making access to funds quicker and more convenient.
Are there any fees associated with using Chime?
Chime prides itself on being a fee-free banking solution. It does not charge monthly maintenance fees, overdraft fees, or foreign transaction fees. However, certain third-party fees, such as those from out-of-network ATMs, may apply. Always check the Chime app for the latest fee information.
Can I manage my savings effectively with Chime?
Chime offers several features for effective savings management. The app includes a ‘Save When You Get Paid’ option, which automatically transfers a percentage of your paycheck into savings. Additionally, it rounds up transactions to the nearest dollar, saving the difference, which helps build savings over time effortlessly.